213/2025-2026
29th August, 2025: In accordance with Article 151 (2) of the Constitution of India, Comptroller and Auditor General of India submits his Audit Reports to the Governor for being laid on the table of the State Legislature.
Accordingly, the Report of the Comptroller and Auditor General of India on Social, Economic, Revenue Sectors and Local Government for the year ended 31 March 2023 (Report No. 1 of 2025), Government of Mizoram was submitted to the State Government on 30th May 2025.
The audit primarily assessed whether the provision of the Constitution of India, applicable rules and regulations made thereunder and various orders and instructions issued by the competent authority are being complied with. Further, audit also assessed whether the programmes, schemes undertaken by government were implemented economically, efficiently and effectively.
This Report contains four Performance Audits (PAs) on (i) Solid Waste Management in Urban Areas of Mizoram, (ii) Disaster Preparedness and Management in Mizoram, (iii) Welfare of Building and Other Construction Workers in Mizoram and (iv) Efficacy of implementation of 74th Constitutional Amendment Act in Mizoram and 10 Compliance Audit paragraphs.
The Report was laid in the State Legislature on 27 August 2025.
A synopsis of the important findings contained in the Report is presented below:
Urban Development & Poverty Alleviation Department
Performance Audit of Solid Waste Management in Urban Areas of Mizoram
The Performance Audit was conducted covering the period from 2017-18 to 2021-2 to evaluate the 2 the extent of implementation of Solid Waste Management (SWM) Rules, 2016 in the urban areas of Mizoram.
Key Findings:
- Actual quantum of solid waste generated could not be determined by the Urban Local Bodies (ULBs) due to lack of weighbridges.
- There was negligible segregation of solid waste in to bio-degradable, non-biodegradable, sanitary waste and domestic hazardous waste before and after collection.
- Vehicles used for collection and transportation of solid waste were not covered and were overloaded.
- Most of the facilities available at Solid Waste Management (SWM) Centre at Tuirial, Aizawl were either not utilised or were non-functional.
- As per satellite images (1 April 2017 to 31 March 2022) it has been noticed that waste were being dumped at the entrance area of the SWM Centre at Tuirial and the area has been expanding over the years due to non-processing of solid waste.
- The untreated solid waste being dumped at the dumping sites in urban areas of Lunglei and Lawngtlai also.
|
|
|
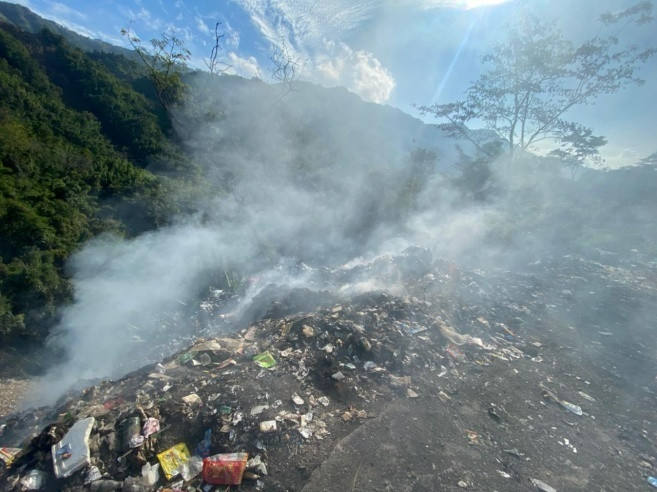
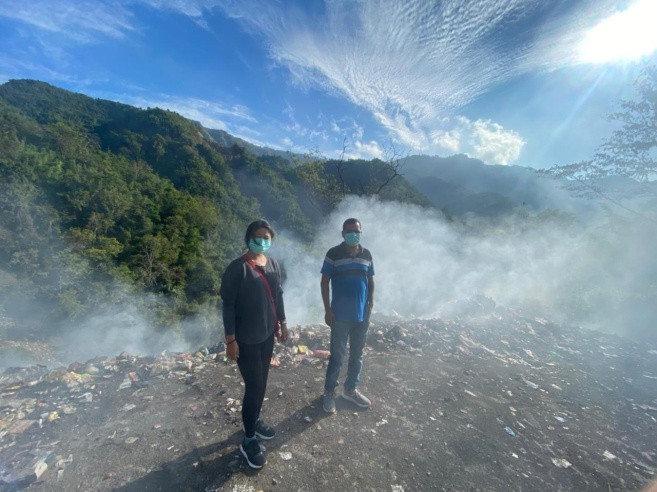
Open Burning at dumping site located at Riangvai Thlanmual, Lunglei causing air pollution
- User charges of ₹ 20.33 crore collected from public by Local Councils were not remitted to Aizawl Municipal Corporation.
- Disposal facilities for domestic Hazardous waste were not functional/available.
- Ground water samples were not tested and ambient air quality was not monitored at the landfill site in Tuirial.
- Audit noticed lack of litter bins in some of the public places resulted in open littering of garbage.
What needs to be done:
- Weighbridges should be installed.
- Solid waste should be segregated at source and disposed properly.
- Solid waste should be transported by covering the waste to prevent spreading of foul odour, littering, etc.
- Local Councils should remit user charges to AMC.
- Environmental impact assessment should be conducted periodically at landfill sites.
- Litter bins should be provided at all public places
Disaster Management and Rehabilitation Department
Performance Audit of Disaster Preparedness and Management in Mizoram
The Performance Audit was conducted covering the period from 2017-18 to 2021-22 to assess the preparedness, the effectiveness and efficiency of the State Government in management of disasters.
Key Findings:
- The State Disaster Management Authority did not review the development plans of the State to ensure that prevention and mitigation measures are integrated therein.
- Regular inspection of landslide prone areas and research studies had not been conducted.
- Soil testing for landslide was done once at Hunthar Veng (in Aizawl) sinking area and material testing had not been conducted in landslide hazard areas in the State
- The State Authority did not prepare separate Standard Operating Procedures for earthquake, landslide, flood, drought, cyclone, cloud burst, etc.
- No checklists for managing and dealing with recurring and frequent hazards that affect the State were prepared by any Department.
- National Building Code for Seismic Zone V has yet to be adopted in the Lawngtlai and Mamit districts.
- No capacity building measures/ training on disaster management had been imparted to medical/ police personnel.
- The State did not establish a dedicated State Disaster Response Force battalion.
- Audit noticed inadmissible expenditure as well as irregularities in incurring of expenditure out of National Disaster Response Fund (NDRF).
What needs to be done:
- State Disaster Management Authority, State Advisory Committee, and District Disaster Management Authority should meet regularly to give overall guidance and monitoring of disaster management at all levels.
- To conduct regular inspection of landslide prone areas so that effective measures can be taken for preparedness and mitigation.
- The Government should train medical staff, para medics, Police, Government officials, etc., on disaster measures and take initiative to enhance public awareness about preparedness for disaster.
- The Government should create a full-fledged State Disaster Response Force to combat disasters.
Labour, Employment, Skill Development and Entrepreneurship Department
Performance Audit of Welfare of Building and Other Construction Workers (BOCW) in Mizoram
The Governor of Mizoram constituted (10 March 2012) the Mizoram BOCW Welfare Fund. The Fund is operated and managed by the Mizoram Building and Other Construction Workers’ Welfare Board and the basic objective of the Fund is to provide a measure of social security for its members who are vulnerable to risks and uncertainties and do not have any other institutional protection based on their employment status.
The Performance Audit was conducted covering the period 2017-18 to 2021-22 to assess the effectiveness and efficiency of the welfare measures and utilisation of the Welfare fund.
Key Findings:
- There was no mechanism in place to ensure registration of every construction work affecting Government revenue.
- Registration of works and workers was made offline as State web portal was not yet developed.
- Labour Cess was not deducted at source for works executed departmentally.
- Migrant workers were not registered with the Board and no special drive and no awareness campaign was conducted by the Board for such workers.
- Audit noticed that there was an overall shortfall of ₹ 10.15 crore in the amount of cess deposited by the respective District Labour & Employment Officers/ Labour Officer of the sampled districts vis-a-vis the amount of Cess received by the Board.
- Safety equipment or appliances like fire extinguishing equipment, safety helmets, etc., were not available in six physically verified construction sites.
- Scheme benefits amounting to ₹ 24.48 lakhs was irregularly made to 390 beneficiaries during 2018-19 to 2021-22 who were State Government employees, Muster Roll Employees, Anganwadi workers, etc., but were also registered as Building/ Construction workers.
- 38 out of 383 beneficiaries of Welfare Pension and two out of 13 beneficiaries of Disability Pension did not receive pension.
- Multipurpose Centre constructed at a cost of ₹ 15.96 crore was being used as offices by LESDE Department and Welfare Board and no provision was made for transit accommodation/ labour shed/ night shelter, etc. as envisaged in the Model welfare Scheme.
What needs to be done:
- The State Government should ensure online registration of establishments and beneficiaries.
- The Department may conduct a special drive to ensure that migrant workers are made aware of the scheme benefits and their registration.
- State Government should set up a mechanism to ensure proper coordination with all Government departments to ensure deduction of cess at source on works executed departmentally and through contractors.
- To identify and de-register all ineligible beneficiaries.
- The Contractors comply with the requirement to ensure the safety, health and protection of construction workers as per Act/Rules.
Aizawl Municipal Corporation
Performance Audit on Efficacy of implementation of 74th Constitutional Amendment Act in Mizoram
The Constitution (Seventy Fourth Amendment) Act, 1992 (74th CAA) provides a constitutional status to Urban Local Bodies (ULBs). The Twelfth Schedule of the Constitution enumerates 18 specific functions to be devolved to Urban Local Bodies to enable them to function as institutions of local self-government. The Performance Audit was conducted covering the period of 2018-19 to 2022-23 to assess whether the ULB is indeed functioning as institution of self-government.
Key Findings:
- Out of 18 functions to be devolved, the State Government devolved 15 functions to the Aizawl Municipal Corporation (AMC).
- There is a lack of clarity on the functional domain of the AMC in the absence of activity mapping / functional assignment of subjects. AMC has full jurisdiction in only three functions.
- There was delay of four years and five months in the constitution of the Second Mizoram State Finance Commission.
- Audit noticed delays ranging from two to 105 days in release of 14th and 15th Central Finance Commission grants to the AMC by the State Government.
- AMC was largely dependent on fiscal transfers in the form of grants ranging between 91.91 per cent to 78.28 per cent of its total revenue during 2018-19 to 2022-23.
- Audit noticed discrepancies in figures of Property Tax collected between Receipt & Payment accounts and property register maintained by AMC.
- The function “Urban Poverty Alleviation” was transferred to AMC however, fund was not allocated towards fulfilment of the function.
What needs to be done:
- State Government may undertake the task of activity mapping/ functional assignment of subjects to AMC.
- Accepted recommendations of State Finance Commission (SFC) should be implemented.
- The State Government may ensure timely release of Central Finance Commission grants to AMC.
- AMC may ensure maintenance of accurate data/information on assessment and collection of Property Tax.
Health & Family Welfare Department
Subject Specific Compliance Audit on Public Health Infrastructure and Management of Health Services
Key Findings:
- During 2021-22, there was an overall shortage of five Community Health Centres (CHCs) (36 per cent) and 34 Health Sub centres (HSCs) (eight per cent) in Mizoram.
- Only Aizawl District Hospital (DH) had all the essential services.
- In DHs significant shortages existed in the cadres of Specialist Doctors which ranged between 39 and 45 per cent.
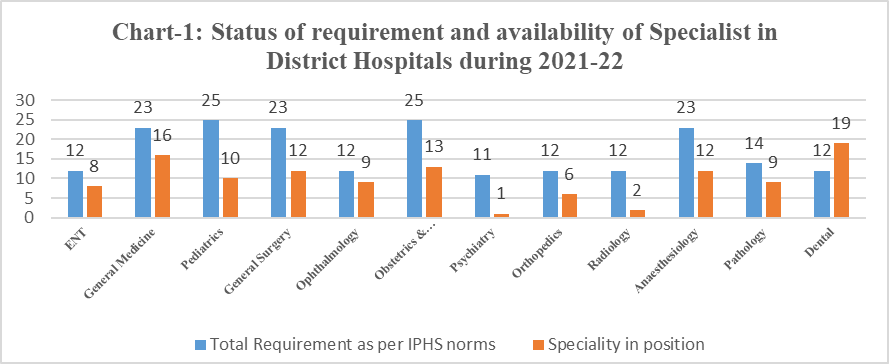
- The overall requirement of doctors in all Primary Health Centres (PHCs) of the State was 57. During 2017-22 the shortage of doctors ranged between three and 14 per cent.
- Audit noticed shortage of paramedics in all the PHCs during 2017-22 ranged between 42 and 44 per cent.
- Dietary services in test checked CHCs and PHCs were operational without any standard operating guidelines.
- All the test checked CHS and PHCs except one were running without NOC from Fire Department.
- Audit noticed deficiencies in infection control facilities, disaster management, power backup, ambulance services and In-patient services in the test checked PHCs and CHCs.
- COVID-19 related infrastructures were not utilised optimally as there was delay in installation of RT‑PCR machine and delay in installation of oxygen generating plants.
- Audit noticed shortage of drugs, equipment, and shortage of staff under AYUSH System of Healthcare in the selected health facilities.
Taxation Department
Subject Specific Compliance Audit on “Department’s Oversight on Goods and Services Tax Payments and Returns Filing” for the year 2017-18
- A review of four Zonal offices disclosed that except Kolasib Zone, the Zonal Offices did not conduct scrutiny of returns even though Standard Operating Procedure (SOP) was issued in May 2022 by the Taxation Department.
- Detailed Audit pointed towards non-compliance on seven major issues: (i) Input Tax Credit (ITC) mismatch between GSTR-3B and GSTR 2A (ii) ITC availed under Reverse Charge Mechanism (RCM) without payment of tax (iii) unreconciled ITC availed (iv) mismatch of ITC in Electronic Credit Ledger (ECL) (v) mismatch of turnover declared in GSTR-9C (Table 5R) (vi) mismatch in tax payable from GSTR-1 (vii) non-payment of interest.
Compliance Audit Paragraphs
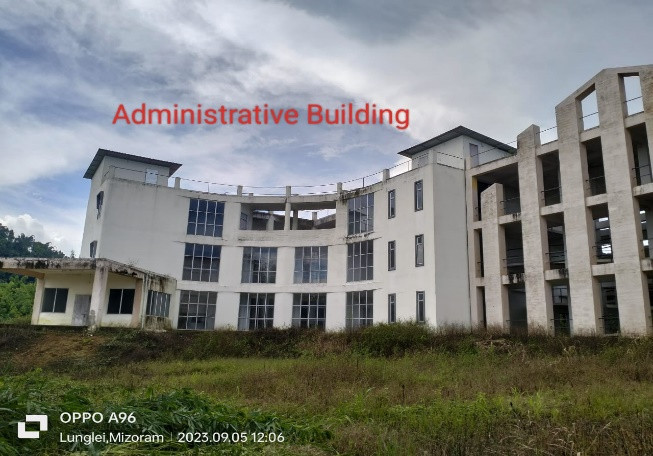
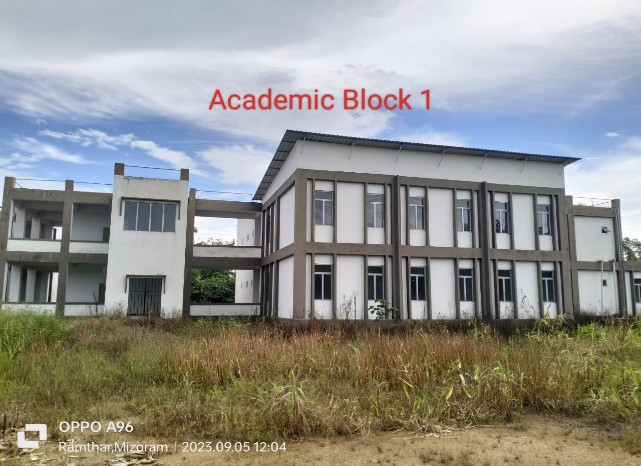
- Idle expenditure: Mizoram Engineering College, constructed at a cost of ₹ 26 crore, remained idle due to the non-provision of staff and funds.
Photographic appearance of the Administrative building and the Academic Block-1 building of the College are shown below:
|
|
- Undue financial benefit to contractors: Public Health Engineering Department made payments of ₹ 1.82 crore before execution/ completion of the works based on false entries in the Measurement Books, resulting in undue financial benefit to the contractors.
- Idle expenditure: Due to incomplete design/ improper planning, the newly constructed State Museum, with an expenditure of ₹ 3.22 crore, was lying idle for more than 12 years.
- Irregular expenditure: The Public Works Department incurred irregular expenditure of ₹ 1.67 crore on formation cutting and disposal of cut materials in the execution of the road-widening project.
- Irregular payments: The Power and Electricity Department made irregular salary payments of ₹ 80.88 lakh to officials who did not perform their official duties.
- Idle expenditure: The Bamboo Development Agency incurred an expenditure of ₹ 4.39 crore on the construction of Export Import Business Training Centre for Entrepreneurs and students at Zuangtui, Aizawl, which was rendered idle.
- Loss of revenue: Due to non-filing of GST returns as per extant rules by two service providers, there was loss of revenue of ₹ 4.90 crore in the execution of Swadesh Darshan projects in Mizoram.
- Irregular Disposal of garbage trucks: Disposal of 45 garbage trucks by Aizawl Municipal Corporation below their book value resulted in loss of ₹ 3.16 crore.